Identify the programme and buyer status first
Start with citizenship, residency status, the programme you are applying under and your current approval stage. A Malaysian returning from abroad, a foreign applicant and a permanent resident can face different transaction requirements. An overseas address alone does not determine the rules.
This guide focuses on the federal Silver, Gold and Platinum property decision. Sabah, Sarawak and special-zone arrangements require their own current checks; do not transfer the ordinary federal table to them. Property ownership also does not itself grant a long-stay pass.
Use your appointed licensed programme operator and Malaysian lawyer to coordinate the process. Eric and Jason can help compare properties and obtain unit information; that is separate from immigration approval, legal consent or a lender’s decision.
Read category price floors alongside acquisition rules
MOTAC’s current property-purchase FAQ publishes the following minimum residence values for the three standard categories, checked on 5 November 2026:
| Federal category | Published minimum residence value | Separate property checks |
|---|---|---|
| Silver | RM600,000 | Relevant acquisition policy and exact unit eligibility |
| Gold | RM1,000,000 | Relevant acquisition policy and exact unit eligibility |
| Platinum | RM2,000,000 | Relevant acquisition policy and exact unit eligibility |
These are programme floors, not universal permission to buy at that price anywhere in Malaysia. State or federal-territory conditions, restricted allocations, title and approved use still need examination. Obtain an assessment for the actual property instead of relying on whichever published figure is lowest.
MOTAC describes special-zone purchases separately. None of the Penang or KL examples below is presented as a special-zone offer. A project’s location near a popular destination does not move it into a different programme or jurisdiction.
Use the later purchase-timing announcement
Read the programme documents together. MOTAC’s 28 May 2025 announcement gives Silver, Gold and Platinum participants one year after pass endorsement to complete the residence purchase. Keep that timetable distinct from an application date, conditional approval or a construction target.
The same announcement addresses qualifying pre-endorsement purchases for fixed-deposit withdrawal. Ask your operator to assess any existing purchase and obtain written confirmation of the documents and dates required. Do not assume every previously owned home is accepted, or that a withdrawal will be available before a purchase payment falls due.
Have your lawyer map booking, consent, sale agreement, financing and completion dates against your programme obligations. An attractive launch schedule is unsuitable if its transaction sequence cannot meet your confirmed requirements. Obtain advice before committing to a deposit or payment deadline.
Which Property Might Suit Your Plans?
These five properties are conditional housing comparisons from the reviewed portfolio, not an MM2H-approved list. They span different home formats and settings. Your operator and lawyer must assess the offered unit and applicant before any eligibility conclusion.
Starting prices are dated gross guides for selected units, not live quotations or confirmation of buyer eligibility. Obtain a current quotation for the exact plan, allocation and intended use.
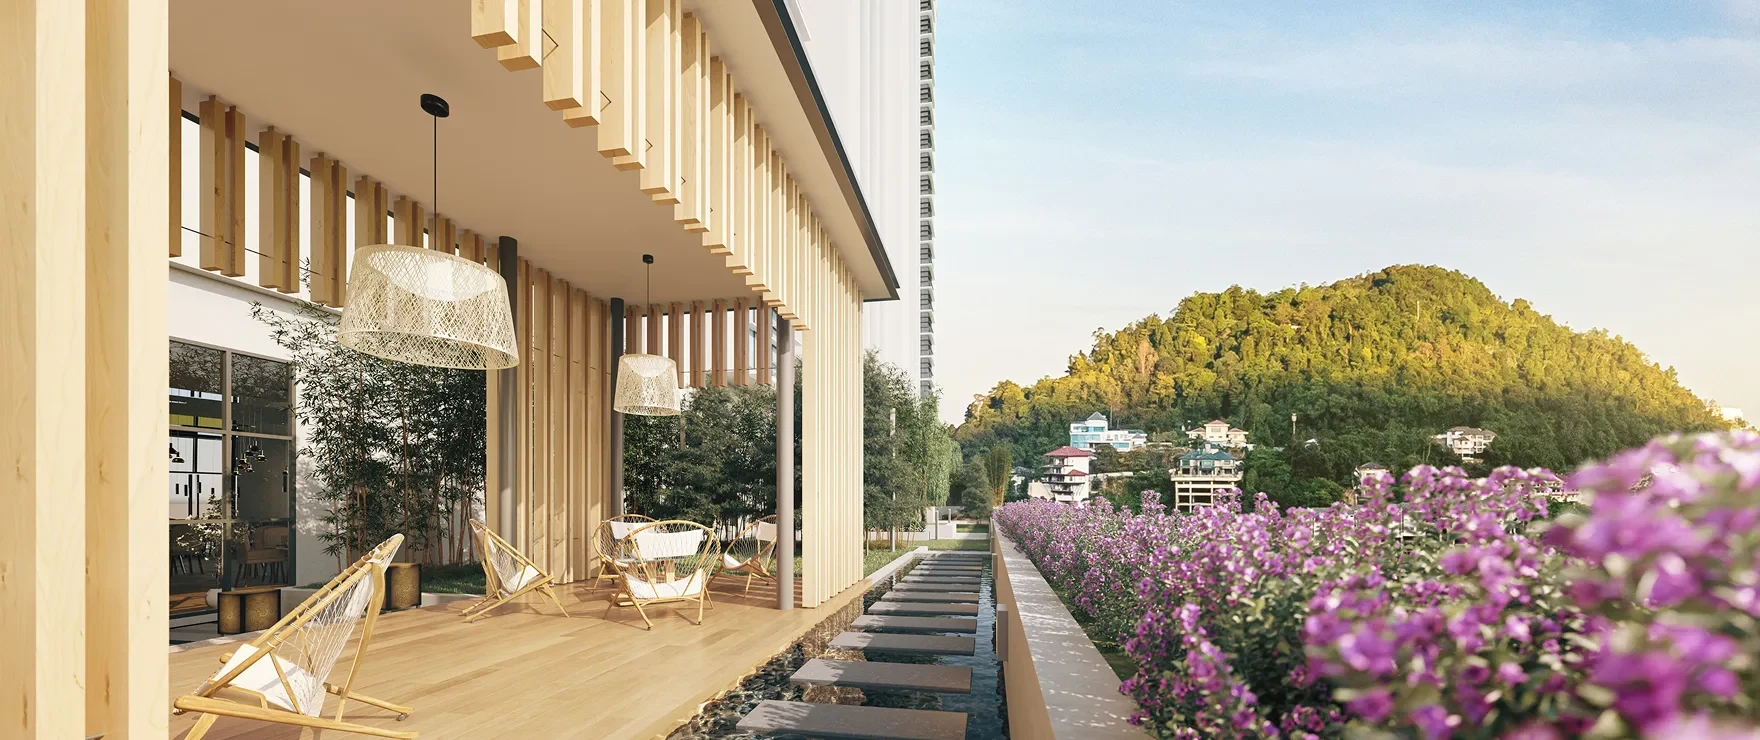
Tanjung Bungah, Penang · Freehold residential condominium · Published plans 1,334–2,195 sq ft
Why consider it: Compare the northern-island home format when family visits and usable bedrooms are part of your long-stay plan.
What to check: Penang acquisition conditions, exact unit eligibility and programme acceptance need separate checks; a RM1.1 million guide does not establish approval.
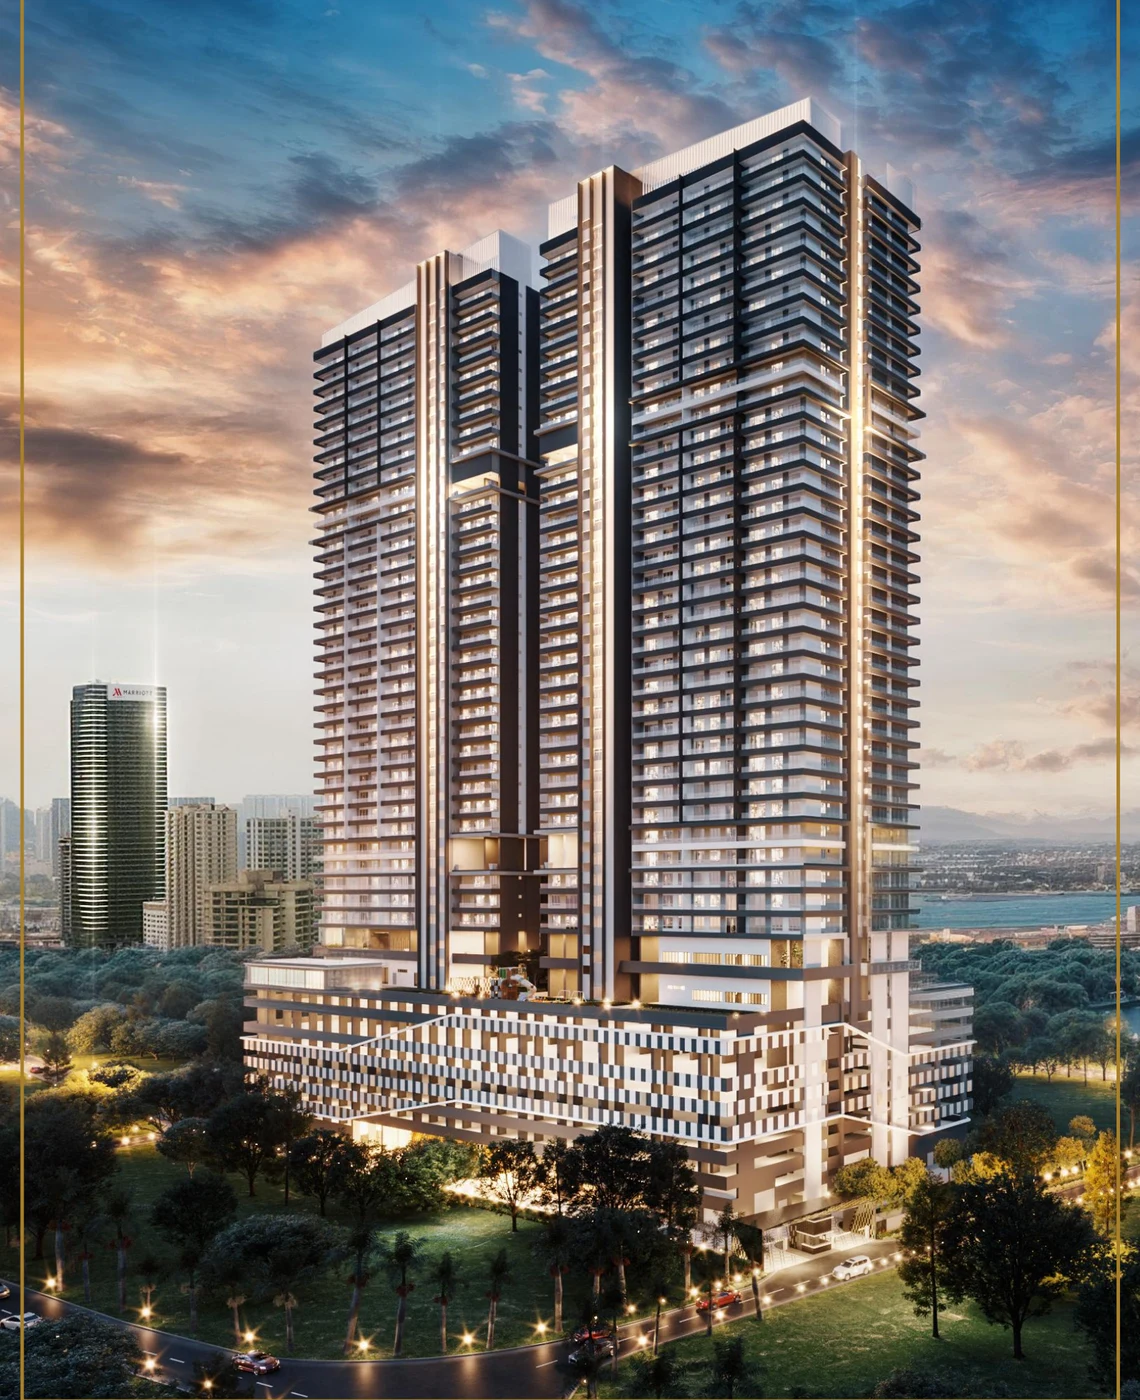
Pykett Avenue, George Town · Freehold residential condominium · Three-bedroom plans 1,206–1,518 sq ft
Why consider it: Compare a George Town routine and a conventional three-bedroom home with your household’s daily destinations.
What to check: Use an eligible current unit quotation, not the approximate entry guide. Confirm acquisition consent, charges and the required property documents.

Damansara Heights, Kuala Lumpur · Freehold serviced apartments · Typical plans 3,380 or 4,090 sq ft
Why consider it: Compare substantial indoor space and bedroom separation for a larger household planning a KL base.
What to check: Approved residential use and programme acceptance must be established. The permit minimum is not a current available-unit offer; typical larger plans require their own quotation.
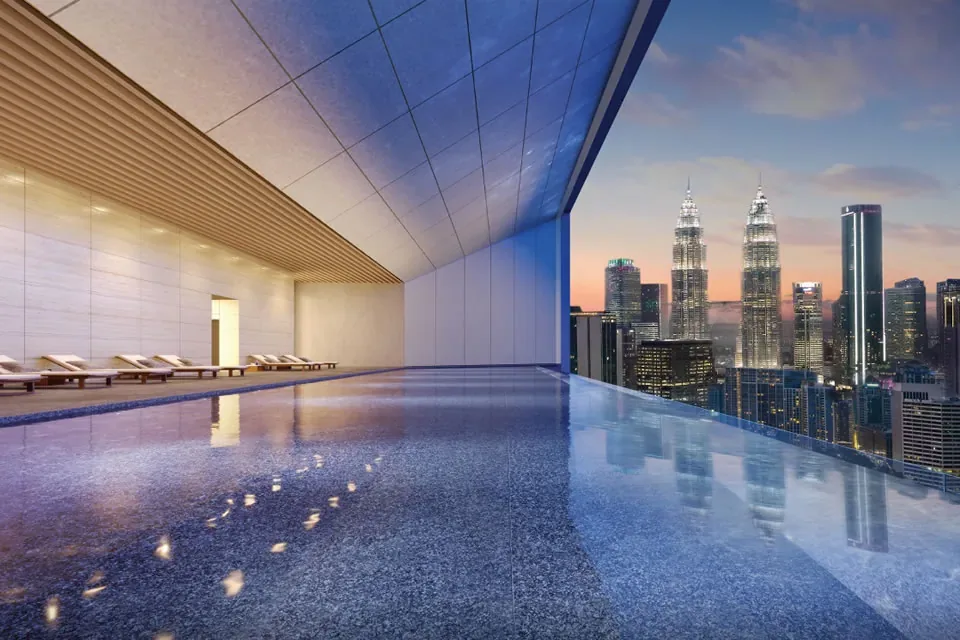
Jalan Conlay, Kuala Lumpur · Freehold serviced-residence reference · Completed-building comparison
Why consider it: A completed-building option lets you inspect an offered city apartment while coordinating your purchase timetable.
What to check: Confirm the exact component, current E/H unit and accepted residence documents. A serviced-apartment label and price above a category floor do not certify MM2H eligibility.
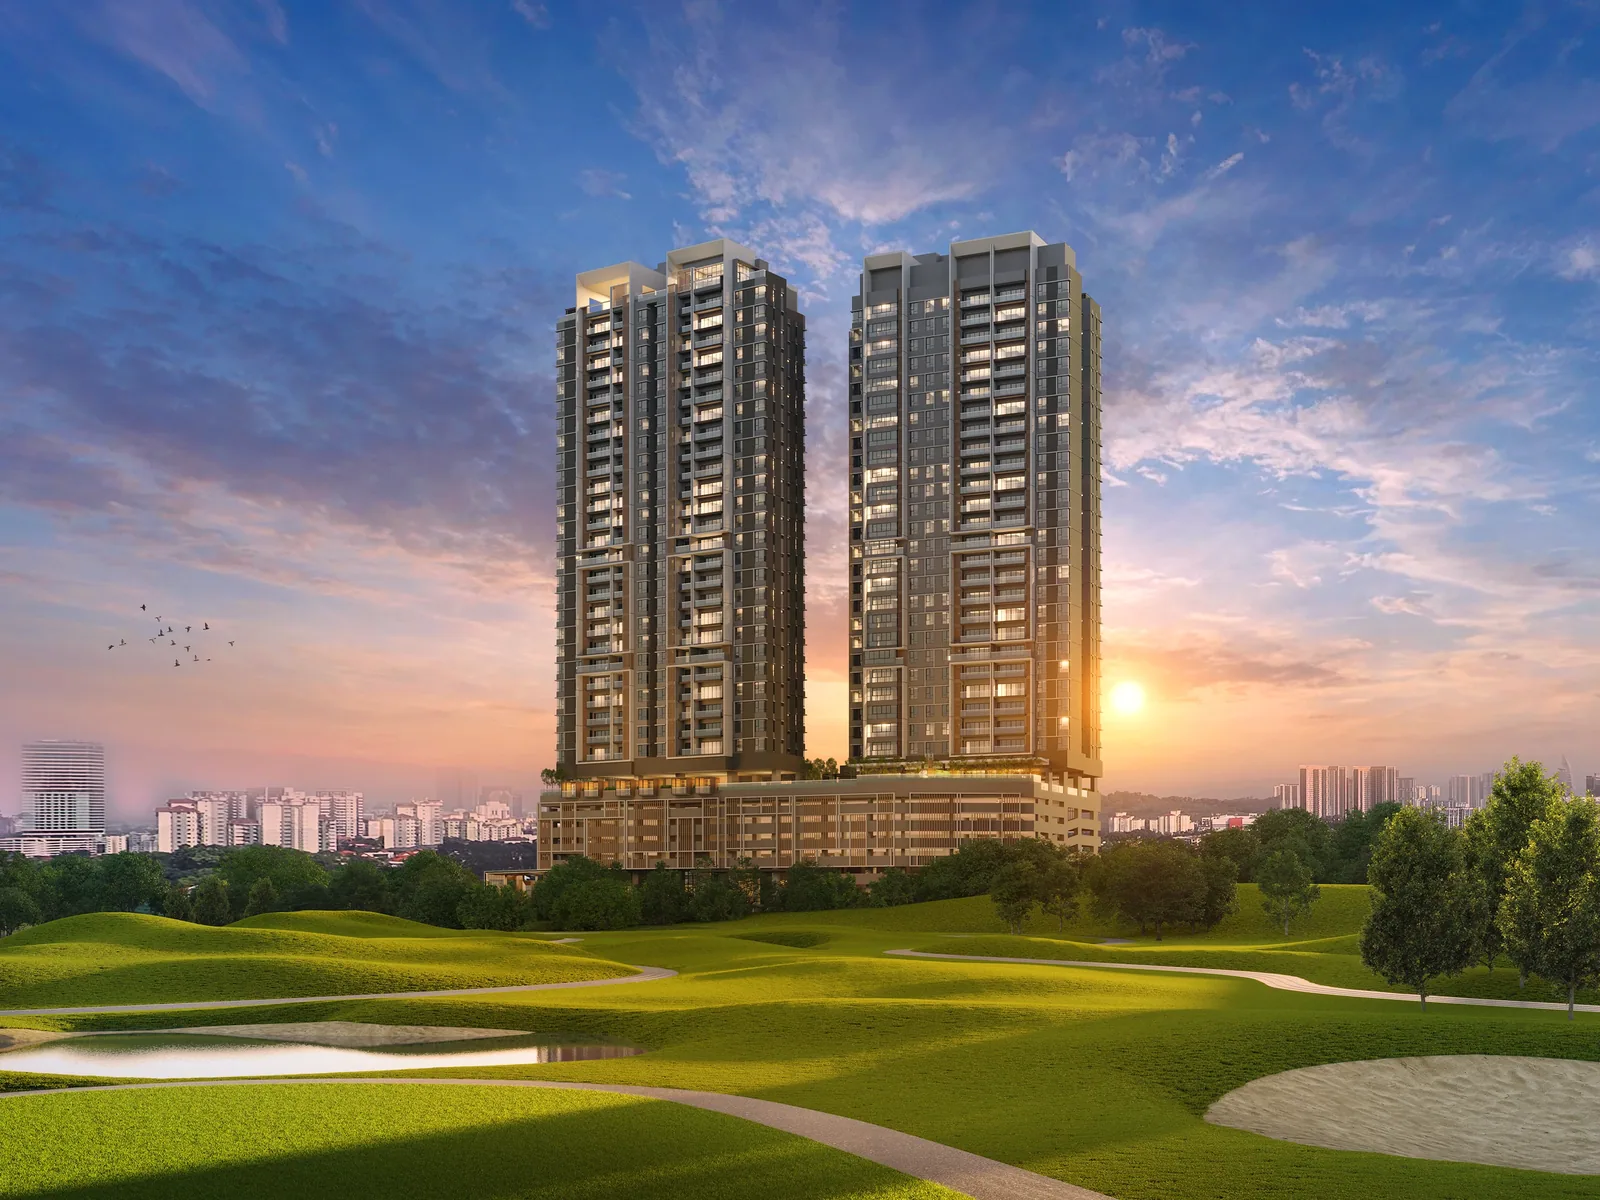
Bukit Jalil, Kuala Lumpur · Freehold residential condominium · Two- and three-bedroom project references
Why consider it: Compare a residential Bukit Jalil home if your family network and preferred routines are in southern KL.
What to check: The saved lower starting figure is allocation-specific and cannot establish a foreign buyer’s available unit. Obtain an eligible quotation and verify delivery and programme requirements.
Build a cash schedule beyond the property price
List deposit and balance payments, transfer duty, legal and loan costs, valuation, consent charges where applicable, furnishing and immediate works. Ask for a current itemised estimate based on your status and instrument dates; an older online tax illustration may no longer fit the transaction.
Programme deposits and fees belong in the same cash schedule but remain separate obligations. Do not count the same money twice as both a protected fixed deposit and immediately available purchase cash. Confirm any permitted withdrawal and its release timing with the relevant parties.
For planning arithmetic only, a RM1.2 million home plus an assumed RM150,000 allowance for acquisition expenses and fitting requires RM1.35 million before separate programme funding and any financing. The allowance is not a tax assessment or a quotation. Replace each heading with the lawyer’s, lender’s and contractor’s figures.
Budget currency conversion, bank-transfer costs and a contingency for delays. A quoted instalment or expected loan amount does not establish bank approval, and a favourable exchange rate should not be assumed to last until completion.
Ask for a unit-specific property file
Request the current gross quotation, approved plan, chargeable area, allocation and seller details. Have your lawyer examine title, use, restrictions and necessary consent; have your programme adviser confirm what residence evidence will be accepted. A brochure summary cannot perform those checks.
For a completed unit, inspect possession, condition and included fittings. For construction purchases, review the offered contract, payment stages and delivery terms. In both cases, confirm the selected unit rather than treating a development-wide range as available stock.
Record what is documented, what requires approval and what remains unanswered. If an essential condition is uncertain, resolve it before a binding commitment. The official acquisition framework is a starting reference, not a substitute for the transaction assessment.
Check annual costs and restrictions on exit
Obtain maintenance and sinking-fund rates, assessment and applicable land-related charges, insurance, utilities, repairs and management rules. The KPKT strata handbook helps explain common-property responsibilities; actual accounts and planned works matter more than a generic monthly estimate.
MOTAC’s resale FAQ describes a ten-year restriction and a higher-value upgrade exception. Ask your operator and lawyer how the conditions apply to your planned transaction and any future change; do not assume unrestricted resale or automatic release from programme obligations.
If later letting is part of your plan, verify permitted use and assess achieved rents, vacancy and owner costs separately. No income or future appreciation is promised. A residence chosen for a programme should also work as an ordinary home within a sustainable budget.
Bring the advisers and the property shortlist together
Send Eric or Jason your programme category and stage, preferred location, household rooms, total budget and moving needs. Share only the information needed for a property discussion; sensitive application documents can remain with your appointed advisers.
Ask for two or three exact units whose plans, costs and transaction timing deserve professional review. Our retirement-home guide explores daily routines, while the Penang Island versus Mainland comparison focuses on residential locations.
FAQs
Does the Silver RM600,000 floor apply to every property in Malaysia?
No. It is a published federal programme floor. Relevant acquisition policies, restrictions, title, approved use and the actual unit still need separate assessment.
Does buying a home give me MM2H approval?
No. Programme participation, immigration approval and property acquisition are separate processes. Coordinate them with the appointed operator and Malaysian lawyer.
When must the standard-category residence purchase be completed?
MOTAC’s 28 May 2025 announcement gives Silver, Gold and Platinum participants one year after pass endorsement. Have your adviser confirm the applicable timetable and documentary requirements.
Are these five projects certified MM2H-eligible?
No. They are conditional comparisons of ordinary homes. Eligibility depends on the applicant, current rules and exact unit; an entry price is not an approval.
Can I assume the home can be resold whenever I want?
No. MOTAC describes a ten-year restriction with a higher-value upgrade exception. Obtain advice on the conditions and approvals applying to your circumstances.
Build a Property Shortlist for Adviser Review
Tell Eric and Jason your programme category and stage, preferred areas, household needs and budget. We can obtain exact-unit information and arrange a consultation or viewing while your appointed operator and lawyer assess programme and purchase eligibility.
- Unit recommendations
- Current availability
Share your preferred day and time on WhatsApp. We’ll confirm your appointment personally.
References & review notes
Reviewed 5 November 2026. Official public sources establish programme information or institution locations, not unit eligibility, route times, operating permission or rental demand. Property formats and gross starting-price guides use the reviewed dated portfolio records linked in each card; confirm the exact offered unit, plan, allocation, quotation and required approvals. No rental income or appreciation is promised. Calculations are hypothetical; AI covers are conceptual. Read the current MOTAC FAQs with the later 28 May 2025 announcement, rather than applying older general wording alone. The shortlisted homes are not certified MM2H eligible. Special-zone and state programmes require separate advice.
 AI-generated lifestyle illustration
 AI-generated lifestyle illustration
 AI-generated lifestyle illustration